Schwab Mobile

Screenshots
Details
- Rating
- 12.87K reviews
- Version
- Varies with device
- Developer
- The Charles Schwab Corporation
Analysis by Norviv
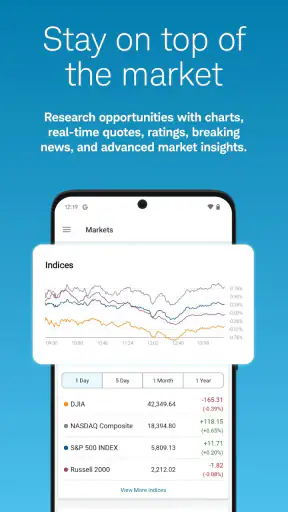
I found Schwab Mobile most useful when I treated it as a practical control panel for an existing Schwab relationship rather than as a general-purpose money app. It brings investing, research, trading, and banking tasks into one place, which can be especially convenient when a household shares a tablet or when one person needs to check an account while another is handling an everyday banking task. The important distinction is that shared access should mean shared device use, not shared credentials.
Developed by The Charles Schwab Corporation, this free finance app has been available since May 25, 2011. It is rated for Everyone, has passed five million installs, and currently sits at an average of 3.1 from roughly twenty-nine thousand ratings and thirteen thousand reviews. Those figures suggest a large, mixed audience rather than a universally smooth experience. My own view is that the app can be valuable for Schwab customers who want several financial jobs in one place, but it is not automatically the best choice for someone seeking a simple budgeting tool or a completely hands-off investing experience.
How Schwab Mobile fits into a shared household
When I think about a shared household, I focus less on putting one app on one device and more on making each person’s role clear. A useful next step is to agree who checks which account and how the device is handed back securely; that keeps convenience from blurring responsibility.
A realistic shared-device routine
Imagine a couple using one household tablet. One person wants to review a brokerage position before work, while the other needs to check a bank balance or move attention to an upcoming bill. On a shared device, having investing and banking tools together can reduce the need to switch between separate apps. That convenience is the strongest household argument for Schwab Mobile: the app follows the financial relationship, not the particular room or device where the task happens.
I would still keep each person’s activity clearly separated. A shared tablet should not become an invitation to leave an account open for the next user. The sensible routine is to finish the task, review which account is currently visible, and sign out or otherwise secure the session before handing over the device. That small habit matters more with a finance app than it would with a weather or shopping app, because a quick glance can expose balances, holdings, transactions, or other private information.
The app’s broad scope also changes how a household should use it. A person checking a bank balance may be only a tap away from investment information or trading tools. That is efficient for the account owner, but it makes accidental navigation more consequential. I prefer assigning a clear purpose to each visit: check cash, review a portfolio, research a security, or handle a banking task. Deliberate use is safer than casually passing the device around with the application still open.
Setup boundaries matter more than convenience
During setup, I would think about ownership before thinking about speed. Schwab Mobile is designed around the customer’s Schwab access, so the main boundary is the account relationship itself. A spouse, roommate, teenager, or visiting relative should not be given another person’s login simply because the device is shared. If two adults need separate access, each person should use their own legitimate account access rather than treating one sign-in as a household profile.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
This is also where a shared-device arrangement can become awkward. The app combines multiple financial activities, so the person who opens it needs to know which account area they are entering and why. I would avoid saving a session on a device that children or guests use freely. I would also avoid discussing account details aloud in a common room while another person is operating the app. The technology can centralize tasks, but it cannot decide which household member should see a balance or approve a transaction.
One useful setup habit is to agree on a simple handoff rule: the person who finishes using the app is responsible for closing the session and returning the device to a neutral screen. That is more reliable than assuming the next person will notice whose information is displayed. It also prevents a rushed user from making a decision while looking at someone else’s account context.
Coordinating money without confusing responsibility
Schwab Mobile can support household coordination when the household already has a clear arrangement. For example, one person might review investments while another monitors bank activity, then they can discuss what they saw. The app helps with access to information, but it does not replace an agreement about who is responsible for a transfer, a trade, or a recurring financial task.
I would never use a quick glance at the app as proof that another person has completed an action. A visible balance is not the same thing as a shared plan, and a portfolio screen is not the same thing as a conversation about risk. If two people coordinate through one device, they should say exactly what has been checked and what still needs attention. That is particularly important when one person is comfortable with investing language and the other is not.
There is a practical trade-off here. Bringing banking and investing together can make a household feel organized, but it can also make the app feel dense. A new user may open it intending to check cash and encounter research or trading areas that are irrelevant to that moment. I found it easier to keep a short personal routine rather than explore every section at once. Familiarity with the few screens used regularly is more useful than trying to master the entire application in one sitting.
Research and trading require a slower mindset
The research and trading side is where I would draw the firmest boundary between convenience and judgment. Having these activities available beside banking information is useful for an experienced investor who wants to review information and act from the same mobile environment. It is less comfortable for a beginner who might interpret easy access as a reason to make fast decisions.
My advice is to separate research from action. First decide what question you are trying to answer, then use the relevant information in the app, and only afterward consider whether a trade is appropriate. On a phone or tablet, the compact format can encourage quick taps and short attention spans. I would not let a child or an inexperienced household member experiment with trading screens merely because the app is available on a shared device.
Another useful distinction is between monitoring and managing. Checking a position while away from a computer can be convenient, especially when the task is simply to understand what is happening. Managing a larger financial decision from a small screen deserves more time and concentration. If the information feels crowded or the account context is unclear, I would stop and return later rather than force a decision through the mobile interface.
Age context and trust at home
The Everyone age classification describes the app’s general content suitability, not a recommendation that every child should use it independently. Finance apps involve private information and potentially serious decisions even when the interface itself is not mature or graphic. In a household, trust and supervision should therefore be based on responsibility, not just the age label.
A teenager might reasonably learn how banking and investing accounts are organized while sitting with a parent. That is different from giving the teenager unsupervised access to an adult’s account. I would use the app as a teaching aid only with the owner present, keeping the lesson focused on concepts such as balances, transactions, research, and the difference between observing and acting. The adult should retain control of credentials and any action that changes money or investments.
For older relatives, the issue may be clarity rather than age. The combined feature set can be helpful if they already understand their Schwab relationship, but a busy screen may be less comfortable than a more focused banking application. I would sit beside them during the first few sessions, establish a small number of repeatable steps, and discourage rushed actions after a confusing prompt. A shared household device should support independence, not quietly turn into a source of dependence on whoever happens to be nearby.
Where it beats simpler alternatives
Compared with a basic budgeting app, Schwab Mobile is better suited to someone whose main need is direct access to Schwab banking and investment activity. A budgeting tool may offer a broader view across different financial institutions, but it usually is not the place I would expect to research and trade within the same Schwab relationship. For a Schwab customer, keeping those tasks together can remove some unnecessary switching.
Compared with a bank-only app, this one makes more sense for a person who wants investment information close to everyday cash management. That combination can be valuable for a household that regularly moves between short-term spending awareness and long-term portfolio review. The trade-off is complexity: a bank-only app may feel calmer for someone who only wants deposits, balances, and transactions.
Compared with a desktop brokerage website, the mobile app is more convenient for quick checks and routine access. I would not automatically choose it for every serious decision, though. A larger screen can make research, comparison, and careful review easier. Schwab Mobile is strongest when mobility matters; the desktop experience may be the better companion when the task requires sustained attention.
Who should use it, and who should skip it?
I would recommend Schwab Mobile to an existing Schwab customer who wants one mobile place for investing, research, trading, and banking. It is also a reasonable fit for a household that shares a device but maintains firm boundaries around individual accounts. The app’s value grows when the user already understands the difference between viewing information and taking action.
I would be more cautious recommending it to someone who wants only a lightweight spending tracker, a cross-provider financial dashboard, or an uncomplicated introduction to personal finance. It may also be a poor fit for a person who dislikes having many financial functions together or who tends to make investment decisions impulsively from a phone. In those situations, a narrower tool or a desktop-first routine may provide better discipline.
The rating of 3.1 gives me another reason to set expectations realistically. A large install base shows that the app is widely used, but popularity does not guarantee that every user will find navigation or account handling equally comfortable. I would judge it by the tasks that matter to me: whether I can reach the right account, understand what I am seeing, and complete routine work without hesitation. Those are more meaningful tests than the download count alone.
My household verdict
After using Schwab Mobile as a finance tool rather than treating it like a simple banking shortcut, I see a capable but responsibility-heavy app. Its biggest strength is the way it puts Schwab banking, investing, research, and trading within the same mobile experience. For an individual customer, that can be genuinely convenient. For a shared household, the same convenience works only when account boundaries, device handoffs, and decision-making responsibilities are explicit.
The best way to use Schwab Mobile is with clear purpose and careful boundaries. Check the account you intended to check, keep credentials personal, separate research from impulsive action, and do not confuse an Everyone age label with permission for unsupervised financial access. Those habits address the main household risks without pretending that an app can manage trust or responsibility for you.
For me, the final decision comes down to the Schwab relationship. If Schwab is already where your banking and investments live, this free app is worth trying because it can reduce the friction of moving between those parts of your financial life. If you want a simpler, provider-neutral, or purely educational experience, I would choose something more focused. Schwab Mobile is most convincing as a consolidated tool for informed account owners, not as a universal money app for every member of the family.
Frequently Asked Questions
01What is Schwab Mobile, and what can I do with it?
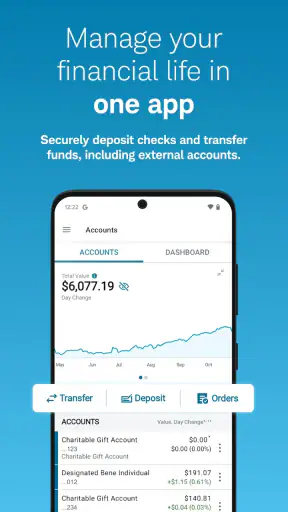
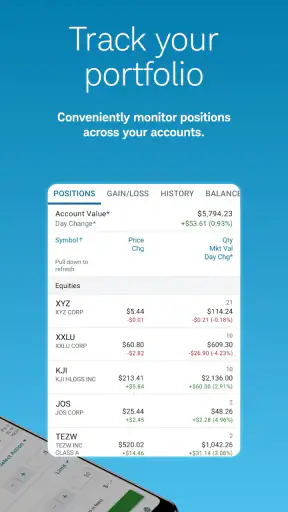
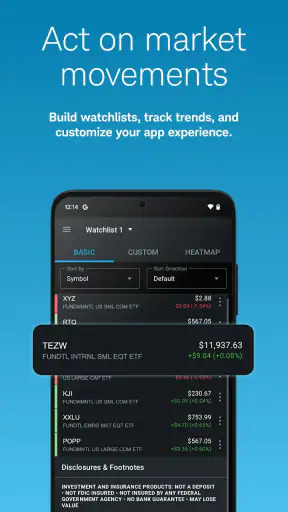
Schwab Mobile is Charles Schwab’s official mobile app for managing eligible brokerage, retirement, banking, and other Schwab accounts from an Android or iOS device. After signing in, you can review balances and positions, monitor watchlists, research investments, place trades, transfer money, deposit eligible checks, view statements, and contact support. Available tools can vary depending on your account type and location.
02Is Schwab Mobile safe to use for investing and account management?
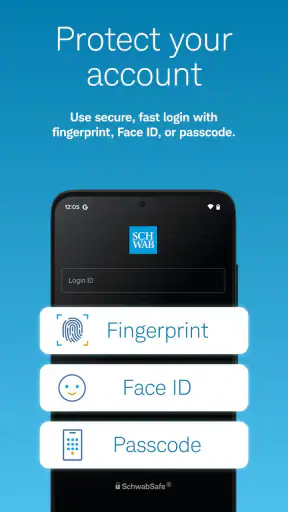
Schwab Mobile includes security features designed to protect account access and financial information, such as encrypted connections, authentication options, alerts, and device-based security features where supported. However, no app eliminates every risk. Download it only from the official Google Play Store or Apple App Store, keep your phone and operating system updated, use a strong unique password, and avoid signing in over unsecured public networks.
03Can I buy and sell stocks, ETFs, options, or mutual funds through Schwab Mobile?
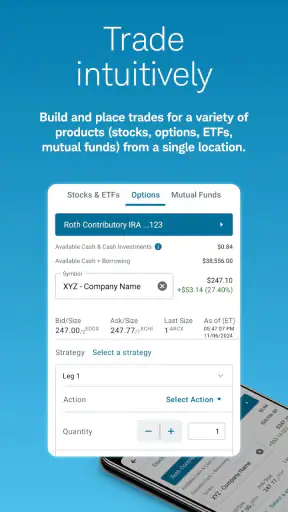
Yes, Schwab Mobile generally allows eligible customers to research and trade a range of investments, including stocks, ETFs, options, and mutual funds. The exact products and order types available depend on your account approval, trading permissions, market conditions, and Schwab’s current policies. Before submitting an order, carefully review the quantity, price, duration, and estimated costs because investing involves potential loss.
04Can I deposit checks and transfer money using Schwab Mobile?
The app typically supports mobile check deposits for eligible Schwab accounts and may allow transfers between Schwab accounts, linked external accounts, and other supported destinations. You may need to complete identity verification or establish linked accounts before using certain features. Deposit limits, processing times, availability of funds, and transfer restrictions can apply, so always review the confirmation details after submitting a transaction.
05Is Schwab Mobile free, and what are the main requirements to use it?
Downloading Schwab Mobile is generally free, although normal mobile data charges from your carrier may apply. To use the app, you need an eligible Schwab account, valid login credentials, a compatible Android or iOS device, and an internet connection. Some investment products, services, or transactions may have separate fees, commissions, or regulatory costs, so check the current Schwab pricing information before proceeding.


